Rent vs Buy Calculator
Compare the true cost of renting against buying a home over time · free, no signup
See Rent vs Buy Calculator in action
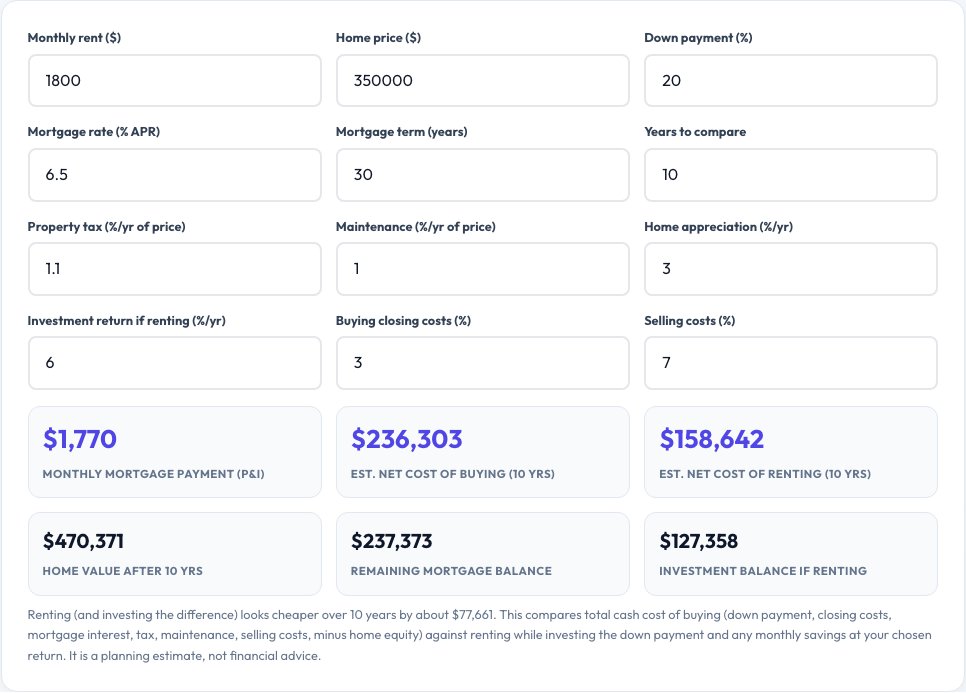
Free Rent vs Buy Calculator
Buying a home is not just the mortgage payment versus the rent — it includes a down payment, closing costs, property tax, maintenance, insurance and eventual selling costs, weighed against what your money could earn if invested instead of tied up in a down payment. This calculator takes your rent, home price, mortgage rate and term, expected home appreciation and investment return, and works out the total cost of each path over your chosen number of years.
It shows the estimated net cost of renting versus buying side by side, so you can see not just the monthly numbers but the long-term picture, including how home equity and opportunity cost of the down payment change the outcome over 5, 10 or 30 years.
Key features
Full cost comparison
Mortgage interest, tax, maintenance, closing and selling costs.
Opportunity cost
Models investment growth on the money not spent on a down payment.
Any time horizon
Compare over 5, 10, 15 or 30 years.
Clear side-by-side result
Net cost of renting vs buying, plus the break-even year.
How to use it
- Enter your monthly rent and the home price you are comparing.
- Enter the mortgage rate, term and down payment.
- Add property tax, maintenance and expected appreciation.
- Read the net cost comparison and break-even point.
Worked example
Example
Rent $1,800/month vs a $350,000 home, 20% down, 6.5% 30-year mortgage → buying breaks even with renting around year 7, assuming 3% home appreciation.
Who uses this tool
First-time home buyers
Decide whether buying makes financial sense right now.
Renters considering a move
Compare the true cost, not just the headline monthly payment.
Financial planners
Model different rate and appreciation scenarios for clients.
Tips for the best results
- Include realistic maintenance costs — 1% of home value per year is a common rule of thumb.
- Do not ignore closing and selling costs; they can offset several years of savings.
- Run the numbers at a few different time horizons, since buying usually favours longer stays.
- Compare against your actual likely investment return, not an optimistic guess.
Common mistakes to avoid
- Comparing only the monthly mortgage payment to rent, ignoring tax, maintenance and insurance.
- Assuming home prices always rise at the same rate.
- Forgetting the opportunity cost of the down payment and closing costs.
Why use AZRS QuickFix?
It is 100% free, needs no signup and has no watermark or usage limits. The tool runs in your browser, so what you type stays on your device, and it works on phones, tablets and desktops. New tools are added every week — bookmark this page or browse the full QuickFix toolbox.
Frequently asked questions
How long do I need to stay to make buying worth it?
It varies by market, but the calculator's break-even year shows the point at which buying overtakes renting for your inputs — often 5–7 years is a common range.
Does this include property tax and insurance?
Yes, you can enter both, plus estimated annual maintenance.
What is the opportunity cost of a down payment?
The investment return you give up by putting that money into a home instead of, for example, index funds — the calculator models this.
Is this financial advice?
No, it is a planning estimate based on the numbers you enter — consult a financial advisor for personal advice.
Does it account for tax deductions?
It focuses on cash costs; mortgage interest deductibility varies by country and situation and is not automatically applied.
What if home prices fall?
Try a lower or negative appreciation rate to see how the comparison changes.